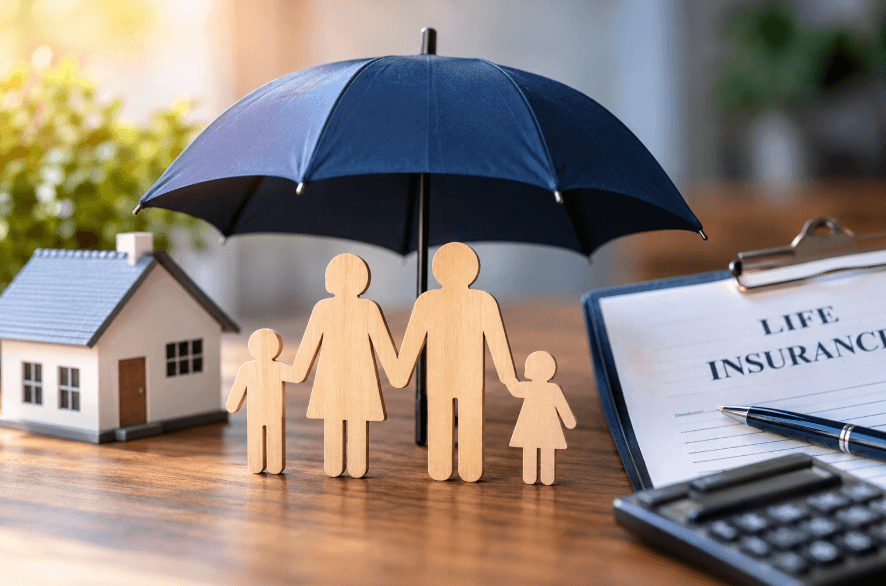
Oklahoma Insurance Commissioner Glen Mulready is encouraging residents to take a closer look at life insurance as part of their financial planning, highlighting several common misconceptions that may prevent individuals and families from securing appropriate coverage.
Life insurance is designed to provide financial protection to beneficiaries after a policyholder dies, helping families manage expenses and replace income. While coverage needs vary depending on household finances and personal circumstances, understanding the basic options can make the decision-making process less intimidating.
Life Insurance Is Not Only for Older Adults
One common misconception is that life insurance is primarily intended for older people. Mulready said coverage can be relevant at different stages of adulthood, particularly as people take on financial obligations such as mortgages or supporting spouses and children.
“Let’s start with one of the most persistent myths: that life insurance is only for older adults. Life insurance is about protecting your income and providing financial stability for the people who depend on you. Life changes quickly. You get married, have children, buy a home or take on new financial responsibilities, no matter your age. Life insurance isn’t about age; it’s about responsibility and planning ahead. Plus, the younger you are, the lower the premiums are, making coverage much more affordable.”
Premiums can depend on factors including age, health, the amount of coverage purchased and the type of policy. Consumers considering life insurance should evaluate their financial obligations and the needs of people who depend on their income.
Employer-Provided Life Insurance May Have Limitations
Many U.S. employers offer group life insurance as part of employee benefit packages. While such coverage can provide an important layer of financial protection, Mulready cautioned that workers should understand its limitations.
“Employer-provided coverage is a valuable benefit, but it’s often limited and usually ends when your job changes. It’s best to think of employer-sponsored group life insurance as a supplement rather than a complete solution. An individual policy tailored to your financial goals offers long-term protection and continuity through life changes, ensuring your family remains covered no matter what.”
Workers reviewing their benefits may want to determine how much coverage their employer provides, whether supplemental insurance is available and what happens to their policy if they leave the company.
An individually purchased policy can provide coverage independently of employment, although costs, benefits and terms vary among insurers and policy types.
Understanding the Main Types of Life Insurance
Another obstacle for consumers is the perception that life insurance products are too complicated. Policies generally fall into several broad categories, each designed to address different financial needs.
Term life insurance provides relatively low-cost coverage for a specified period and does not typically accumulate cash value. It can be used to protect dependents during years when financial obligations are particularly high.
Whole life insurance provides lifelong coverage with fixed premiums and a guaranteed death benefit, provided policy requirements are met. These policies also include a cash-value component that can be accessed under certain conditions or received if the policy is surrendered.
Universal life insurance is another form of permanent coverage. It generally offers more flexibility in premiums and death benefits while allowing the policy to accumulate cash value that may be withdrawn or borrowed against, subject to the policy’s terms.
Consumers should consider how much coverage they need, how long protection will be necessary and whom they want to designate as beneficiaries before selecting a policy.
Oklahoma Consumers Encouraged to Review Coverage Needs
Mulready said consumers do not have to navigate insurance decisions alone. Licensed insurance agents, comparison tools and consumer resources from insurance regulators can help people better understand their options.
The Oklahoma Insurance Department’s Consumer Assistance Division also provides support for residents with questions about policies or other insurance-related matters.
“Life insurance remains one of the most meaningful ways Oklahomans can protect their families. Don’t hesitate to seek guidance, ask questions and make informed decisions about your coverage.”
Oklahoma residents with questions about life insurance or other insurance matters can contact the Oklahoma Insurance Department at 800-522-0071.
For households reviewing their financial plans, life insurance needs can change over time. Major events such as marriage, having children, buying a home or changing jobs can provide an opportunity to reassess existing coverage and determine whether it continues to meet a family’s financial needs.